NZX Bought This Startup for $7 Million. Then Everything Unravelled
Synopsis
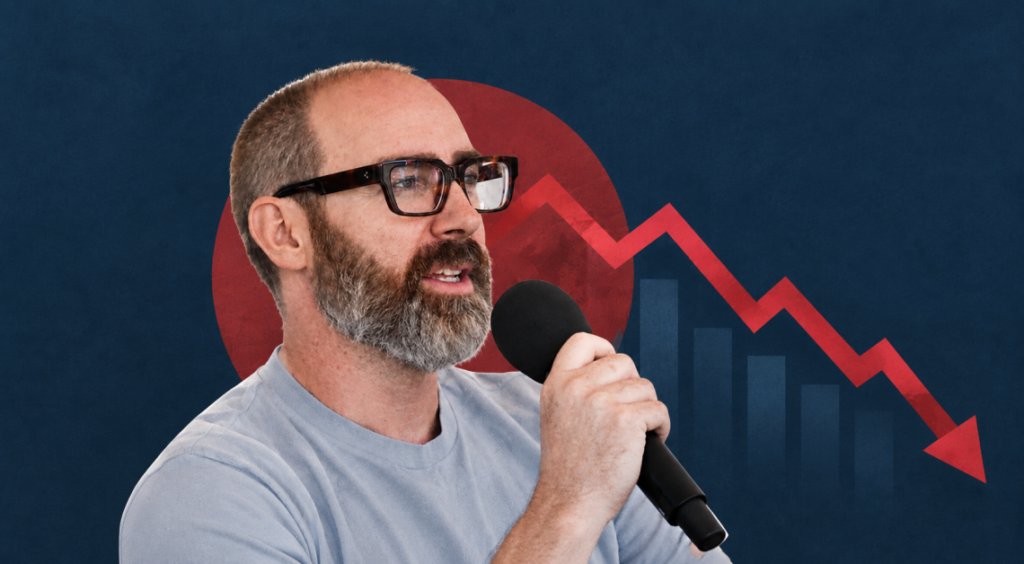
Clear Grain looked like a promising grain-trading business when NZX bought it for about A$7 million in 2009. But ambitious growth targets were missed, expectations around GrainCorp did not materialise as expected, and the deal eventually ended in a lengthy legal battle.
An acquisition may seem appealing on paper, but for a business buyer that initial promise can become something quite different once the ink dries. Exactly that happened with Australian online grain-trading business Clear Grain Exchange linked to entrepreneur Dom Pym. New Zealand Exchange (NZX) acquired the business in 2009 for around A$7 million, plus performance-based payments of up to a further A$14 million. It was going to be a grain business that would scale very rapidly and process millions of tons right from the get-go. The anticipated levels of trading however, never materialised, the extra payments were never triggered and the acquisition came to be the subject of a protracted legal battle between NZX and its previous owners.
What Was a Clear Grain Exchange?
Clear Grain Exchange was an electronic platform created with the goal of simplifying grain trading for participants in the grain industry. Its business model interlinked growers, buyers and other market participants through an online platform.
The concept emerged at a time when the grain industry in Australia was undergoing some significant transitions. Clear was built to capitalise on industry changes, providing a more direct method of grain trading.
Prior to the acquisition, Clear had developed a pool of participants and was attempting to establish itself as a credible alternative service in the Australian grain space. NZX believed the company had technology assets that could help it on its path to take advantage of agricultural market opportunities.
NZX was not just drawn to the tech. The exchange thought the platform could tap into vast trading volume, and grow into a more significant overall business in agriculture.
NZX Buys the Business
In 2009, NZX reached an agreement to buy the assets required to operate the Clear electronic grain trading platform. This included a purchase price of A$6.4 million/A$7 million based on different ways the transaction was reported through various company documents.
The key element of the deal was that NZX should pay considerably more if Clear achieved specific performance benchmarks.
A further A$7 million was deferred dependent on the volume of grain transacted through the platform. A further A$7 million was tied to the development and operation of an online agricultural portal. Put simply, NZX was not only buying what Clear was at the time. It was also agreeing to pay more if the company achieved the growth it had been expecting. That made Clear’s future performance key to the economics of the agreement.
The Big Growth Target
One of the biggest hopes associated with the agreement was how much grain Clear would actually have to trade.
By June 2010, the company expected to be trading 1.5 million tonnes. This projection was closely studied later in the High Court judgement. The financial projection assumed the business would earn annual revenue of approximately $2 per tonne by processing around 1.5 million tonnes of grain.
To know why this mattered, the target was not just an empty number on a presentation. This was related to the prospective extra payment that NZX may owe under the acquisition agreement.
In case Clear didn’t qualify for the first target, there were subsequent targets based on increased trading volumes. According to NZX’s own annual report released in 2012, Clear had traded insufficient volumes by June 2012 meaning that the $A7 million payment linked to grain trading was not made. The other payment was for a planned agricultural portal, which also did not achieve the necessary functionality by the deadline and as such that sum was likewise not disbursed.
The issue thus was becoming evident: the company was not performing to the extent that had been anticipated when the acquisition had been agreed.
The Gap Between Expectation and Reality
Our biggest problem was what NZX thought the business would achieve versus what it actually achieved. The High Court ruling said the earlier estimates made to NZX indicated that trading 1.5 million tonnes was within reach. It also agreed that the projections demonstrated its ability to carry on at the expense level suggested in the plan.
The court however discovered that there was also another significant matter. Dom Pym, and Grant Thomas of Clear, which set up the grain exchange for NZX, expected that the regulator would be spending far more than $440,000 on marketing and systems development. This expectation was not apparent on the financials given to NZX.
Put simply, it seems that both sides came into the deal with differing expectations of what post-acquisition would look like. NZX anticipated the business could reach that level of trading without additional expenditure envisaged by previous owners. That difference became relevant after NZX took over the business.
The GrainCorp Problem
GrainCorp, one of the big ticket items on this list and an important Australian grain handling business, faced other major issues.
If NZX was willing to believe Clear would trade grain owned by an enormous quantity of GrainCorp through the Clear platform, then the court ruled that’s what it believed. However, after it acquired the company, NZX realised GrainCorp was not trading on the platform to an extent that NZX had anticipated. The court also heard that GrainCorp’s head of trading was against GrainCorp using Clear to trade.
A huge problem arose when expectations over the relationship with GrainCorp formed a key part of NZX’s forecasts for future trading volumes. This left a gaping chasm between the volume of grain NZX expected would be cleared through its platform and that which was actually being traded.
The Business Needed More Support
It was not just about whether the projections of Clear were realistic. Another major issue was what happened after NZX purchased the business, and how much assistance it provided.
The previous owners also alleged that NZX had failed to properly resource Clear, which they said would have had a fair chance of reaching the performance targets contained within the sales agreement.
The High Court eventually accepted one of those arguments. It found NZX had not adequately considered the net external resources that would have allowed the business to meet the earn-out targets as required in its sale agreement. But that did not mean the former owners had won the case.
It ruled that they also weren’t able to demonstrate that Clear would have been able to meet the targets with more resources. As a result, they were awarded zero damages.
This is an important distinction. NZX did not comply with a contractual duty about resourcing, the court found, but it said there was “insufficient evidence” of a loss that could be claimed as money owed.
The Legal Fight Over the Dispute
Clear, which underdelivered, soon turned its dispute into a full-fledged legal battle.
NZX’s claims for breach of contract as it takes action against entities Ralec Commodities and its associated company Ralac Interactive, and three individuals (Grant Thomas, Dom Pym and others). NZX claimed information and representations were made to it prior to the acquisition and had a significant influence on its decision to acquire Clear.
The previous owners denied NZX’s claims, putting up their own counterclaims. Among other arguments, they said NZX was too stingy with the resources required for the business to meet targets that had been agreed. The case remained ongoing for years before going to trial.
This was more than two companies in a legal spat. The High Court trial spanned 11 weeks and scrutinised the deal, whether business forecasts were met, what each party expected back from the other and how NZX conducted itself after gaining control of Clear.
What the Court Finally Found
However, the High Court’s decision in 2016 was not an outright victory for one side and defeat for the other. The case also included four out of five misrepresentation claims from NZX, with the court ruling in favour. However, NZX received no compensation as it could not prove a quantifiable financial loss from the misrepresentations.
By contrast, they partly succeeded in their claim against the former owners. The court held that NZX had not properly taken into account the resources necessary for Clear to be given a reasonable chance of achieving the earn-out targets. But once again, no damages were awarded to the owners, who failed to show that improved funding of pension arrangements would have delivered those targets.
In a statement, NZX itself described the outcome as “nil-all draw”, as neither party was awarded damages.
And so the court ruling reveals just how complicated a mess the Clear deal was. There were issues about the assumptions underlying the business, uncertainties around the information given prior to acquisition, disputes relating to funding and resources required and a huge variance between forecast earnings and those actually realised in trading.
The Cost of a Missed Acquisition
It turned out that Clear would fall far short of the expectations set for the deal The additional A$7 million grain trading-linked payment also went unpaid as the requisite trading volumes were not achieved. NZX also did not make the A$7 million separate payment associated with the agricultural portal, because it did not complete and operationalise the portal by a deadline acceptable to NZX. After holding Clear for years and fighting the lawsuit, NZX sold off the firm.
NZX had booked a loss on its divestment of Clear Grain Exchange and other assets in its financial reports by 2016. NZX said the 2015 High Court ruling had brought a resolution to its long-running Ralec litigation without awarding damages to either party and no appeal was pursued.
What Went Wrong with Clear Grain?
The Clear Grain story is about the mistakes made. Aspiring to ambitious growth, the firm had a target going into its NZX deal. The future relied on big trading volumes, including speculation about activity related to GrainCorp. However, trading did not take place at the level that NZX had previously forecast.
At the same time, previous owners wanted to make sure that NZX would have had to invest much higher sums and resources in growing the business. The court later held that NZX failed to account for the resources required to achieve the earn-out targets.
The outcome left a tough situation, as the expectations on both sides did not mirror what occurred post-acquisition.
Clear was purchased for prediction that it was able to develop into a bigger grain-trading company. Instead, missed performance targets, failed to trigger additional payments, and a deteriorating relationship between the parties descended into years of litigation and business divestiture.
So, while the Clear Grain case read on its surface like a simple tale of a company that fell off a precipice, in fact one might be better off classifying it as an example of what can happen when you acquire something with expectations for growth and performance that are not met. The court was also revealing that who bears responsibility for the outcome was more nuanced than merely casting blame on either side. Involved in the dispute were not simply pre-acquisition expectations but also how the business should be supported post-acquisition.
The Clear Grain chapter was far from the end for Dom Pym. His next business move took him in a completely different direction, and eventually to 1 million customers. Here’s what happened next.
At Inspirepreneurs Magazine, covering entrepreneurship, business failures, and the human stories behind the world's most ambitious founders. She writes at the intersection of strategy and storytelling.
You Might Also Like
Giovanni Ferrero: A Visionary Entrepreneur Redefining the Confectionery Industry
Microsoft-OpenAI Partnership Escapes UK Watchdog Scrutiny
